Plain language
What is a loan?
You borrow a sum. You return it, plus interest, on a clock. Click each part. Then pick the product that matches — or WhatsApp the desk.
The contract
What a loan is
Money you take now. You repay it later, with interest.
A loan is a contract. A bank or NBFC gives you a sum (the principal). You give it back over a fixed time (the tenure), plus a charge for the use of that money (the interest, or ROI). Until it is repaid, you owe the lender — not WishON. We are a Direct Selling Agent: we prepare and file the paper. They sanction and disburse.
WishON desk
Types, eligibility, apply, benefits
What each loan is. Who qualifies. How to file through WishON Finserv Solutions. Why that is better than five bank apps. Indicative — the sanction is the lender’s.
Explanation
Personal Loan
WishON’s core product. Unsecured. Tenure up to 8 years. Amount typically ₹75 lakh to ₹1 crore depending on the bank or NBFC and the overall profile. Originated with private banks including HDFC Bank, ICICI Bank, Axis Bank, and Kotak Mahindra Bank, and with NBFCs. Not with nationalised banks. Rate starts at 9.99% p.a.
Unsecured cash — no house, no gold. Typical purposes include a wedding, home renovation, holiday, car or two-wheeler, and a child’s education. EMI every month. Private banks and NBFCs only. A new home is originated as a home loan, not as a personal loan.
- From
- 9.99% p.a.
- Amount
- ₹50,000 – ₹1 Cr
- Tenure
- Up to 8 years
- Who it suits
- Salaried
Products
Loans we file
Personal unsecured up to ₹1 Cr from 9.99% p.a., with private banks and NBFCs. Home loan up to ₹20 Cr from 7.25% with nationalised banks. LAP up to ₹50 Cr. Overdraft from 11.50%, up to 9 years. A balance transfer is filed only after the existing loan and the receiving lender’s terms are read — WishON does not publish a transfer rate it cannot evidence. Rates and tickets are indicative; the sanction letter is the lender’s.
 Major desk
Personal Loan
Our busiest desk. Unsecured credit up to ₹1 Cr and 8 years, from 9.99% p.a. depending on profile.
Indicative from
9.99% p.a.
Up to ₹1 Cr · 8 yr
 Major desk
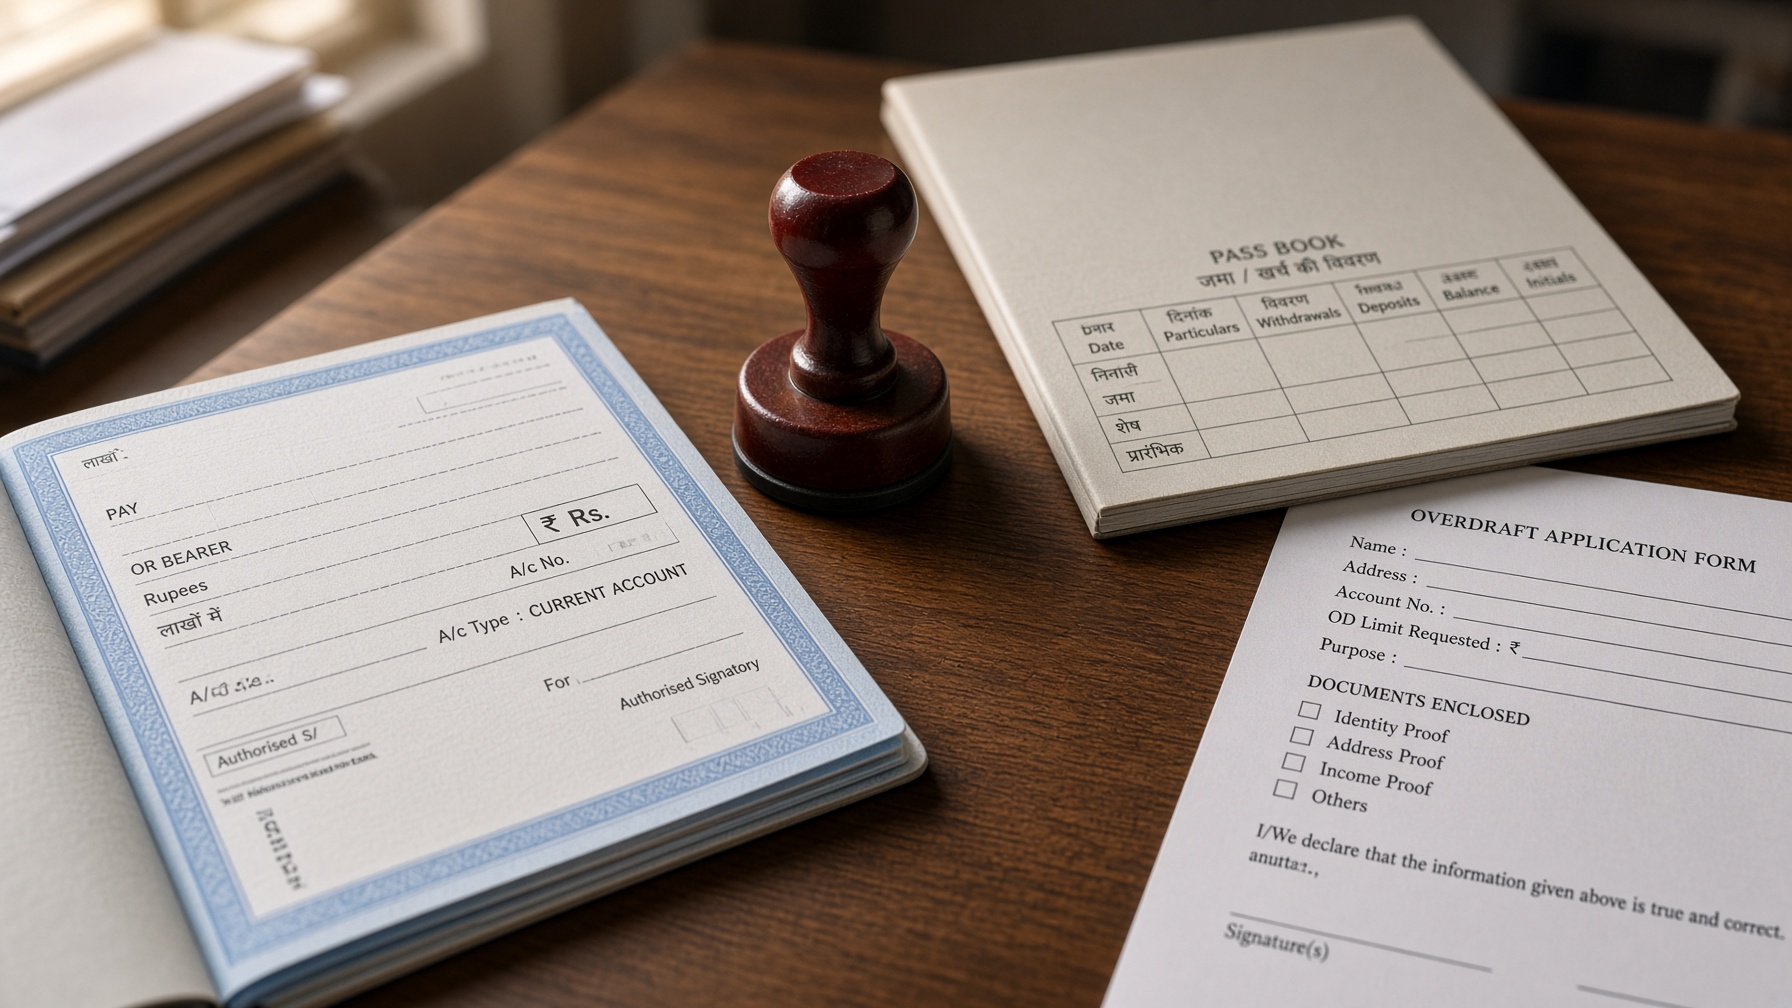
Overdraft
Our other major desk. OD and cash credit — limits up to 9 years. Rate from 11.50% p.a. Limit typically within 24 working hours.
Indicative from
11.50% p.a.
Up to ₹5 Cr · 9 yr
Business Loan
Term credit up to ₹1 Cr unsecured — from proprietorship to public limited, trusts, and institutions.
Indicative from
11.00% p.a.
Up to ₹1 Cr · 7 yr
Home Loan
Buy, build, or balance-transfer — nationalised banks, from 7.25% p.a., tickets up to ₹20 Cr.
Indicative from
7.25% p.a.
Up to ₹20 Cr · 25 yr
Loan Against Property
Raise funds on a clear residential or commercial property — up to ₹50 Cr.
Indicative from
9.25% p.a.
Up to ₹50 Cr · 15 yr
Credit Cards
Private-bank and NBFC cards — lifetime-free, premium, and business variants.
Indicative from
1.49% p.m.
Up to ₹15 L · 1 yr
Compare
Overdraft vs personal loan
Personal starts cheaper on the board — 9.99% vs 11.50%. Overdraft can still cost less if you do not draw the full limit. Floor rates only. Not a sanction.
| Personal loan | Overdraft | |
|---|---|---|
| Floor ROI | From 9.99% p.a. | From 11.50% p.a. |
| Interest charged on | The full outstanding, every month, as you amortize. | Only what you have drawn, for the days it is drawn. |
| Monthly cash out | Fixed EMI (principal + interest). | Interest on utilisation. Principal stays until you repay it. |
| Tenure | Up to 8 years. | Limit up to 9 years, reviewed. |
| Clock | Same-day login / disbursal on eligible files; else 24–48 working hours. | Limit typically within 24 working hours. |
| Ends at | Zero. The loan is closed. | Whatever you still have drawn. It is a line, not a term loan. |
| Lenders | Private banks and NBFCs — not PSU banks. | Private banks and NBFCs; salary-account OD or business CC. |
Who we file for
Business credit, overdraft, and LAP for these constitutions. Personal loans for salaried and government employees.
- Proprietorship
- Partnership
- LLP
- Private Limited
- Public Limited
- Unlimited company
- Government employee
- Trust
- NGO / Society
- Private school & college
- Hospital